How Can a Business Protect Its UPI and Payment Accounts From Fraud?
UPI's speed and ubiquity make it a favourite fraud target for Indian businesses — here's the practical control set that actually reduces exposure.
💡 In Simple Terms (For Beginners)
UPI payments are instant and hard to reverse, which is exactly what makes them attractive to fraudsters — protecting your business account means verifying requests before paying, not after, since there's often no undo button once money moves.
- UPI's speed removes the delay window that used to let a business catch and reverse a fraudulent transfer.
- QR code tampering, fake payment links, and impersonation are the main UPI-specific fraud patterns businesses face.
- Verification before payment, not recovery after, is the only reliable defence given how fast UPI settles.
THREAT INTEL · September 30, 2026 · 6 min read · By Hardik Patel
How can a business protect its UPI and payment accounts from fraud? Because UPI transfers settle almost instantly and are difficult to reverse, protecting a business UPI account depends entirely on verifying a payment request before sending money, not on being able to recover it afterward.
Why UPI Fraud Is Hard to Reverse
UPI's core design advantage — near-instant settlement — is also exactly what makes fraud on it so damaging, because the window banks and businesses traditionally relied on to catch and reverse a fraudulent transfer barely exists once a UPI payment clears.
This means the entire defence has to shift earlier in the process — to verification before a payment goes out — rather than relying on recovery after, which was already covered in detail in our payment verification checklist.
The Main UPI-Specific Fraud Patterns
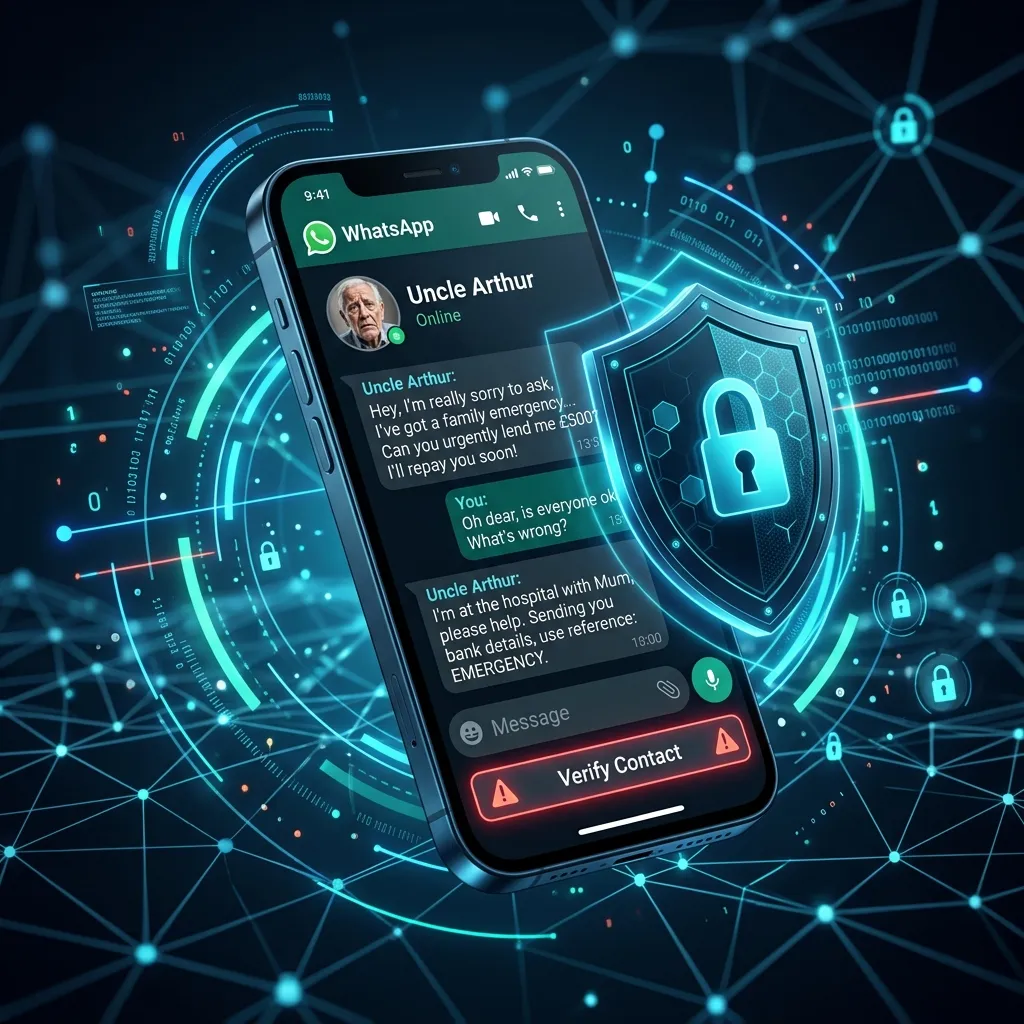
The most common UPI-specific fraud patterns businesses face are QR code tampering (a fraudulent sticker placed over a real payment QR), fake payment collect requests disguised as refunds, and vendor or leadership impersonation requesting an urgent UPI transfer.
Each of these relies on the same underlying weakness — an employee acting on a request without independently verifying it — which is why the fix is procedural, not purely technical.
Practical Protection for a Business UPI Account
- Never approve a UPI "collect" request from an unknown source — a collect request asks money to move from you, and a fraudster disguising it as a refund is a common pattern.
- Physically inspect any displayed payment QR code regularly for signs of a tampered overlay sticker.
- Apply the same callback-verification rule used for any other payment request — never confirm through the same channel the request arrived on.
- Set transaction limits appropriate to routine business activity, so an unusual large transfer requires additional approval.
Key Takeaways
- UPI's near-instant settlement removes the recovery window fraud protection traditionally relied on.
- QR tampering, fake collect requests, and impersonation are the main UPI-specific patterns.
- Verification before payment is the only reliable defence, not recovery after the fact.
Frequently Asked Questions
Q: Can a fraudulent UPI transfer be reversed?
A: Recovery is possible in some cases through your bank and cybercrime reporting channels, but it's far from guaranteed and often slow — prevention through verification before payment is far more reliable than relying on reversal.
Q: What is a UPI collect request, and why is it risky?
A: A collect request asks the recipient to approve money moving out of their account, rather than receiving money — fraudsters disguise these as refunds or minor charges, hoping the request is approved without close reading.
How iTechFixr Can Help
Our Human Firewall training covers UPI-specific fraud patterns directly, alongside the broader payment verification habits that protect a business across every payment channel, not just UPI.
Need Help With This?
Talk to Hardik directly about your organisation's cybersecurity needs — get a tailored response within 24 hours.
